Who Sent Me PO Box 140 Normanton WF6 1YA Debt Letter?


For free & impartial money advice you can visit MoneyHelper. We work with The Debt Advice Service who provide information about your options. This isn’t a full fact-find, some debt solutions may not be suitable in all circumstances, ongoing fees might apply & your credit rating may be affected.
For free & impartial money advice you can visit MoneyHelper. We work with The Debt Advice Service who provide information about your options. This isn’t a full fact-find, some debt solutions may not be suitable in all circumstances, ongoing fees might apply & your credit rating may be affected.
Receiving a debt letter from PO Box 140 Normanton WF6 1YA can be confusing and scary. But don’t worry; we’re here to help you understand what it means and what to do next.
Every month, over 12,000 people visit this site for advice on debt issues, just like this one. You’re not alone.
In this article, we’ll explain:
- Why you might be getting letters from debt collectors
- Who uses PO Box 140 Normanton WF6 1YA
- What you can do if you get a letter from there
- How to lower your repayments
- What to do if you’re not sure the debt is yours
We know how worrying it can be to deal with debt collectors; some of us have been there too. Don’t worry; with the right information, you can handle this situation well.
Ready to find out more about how to handle debt letters and protect your rights? Let’s get started!
Who uses PO Box 140 Normanton WF6 1YA?
It seems that several businesses, companies and organisations use the PO Box 140 Normanton WF6 1YA return address for their mail.
I’ve listed some here:
- Banks and other financial institutions
- Credit providers/lenders which includes Britannia Personal Lending
- PPI companies
- Debt collection agencies
It’s worth noting that Lloyds Banking Group is one of the major banks to use the return address too.
Lots of people ask if letters with this address are a scam or not. Check out the question someone asked below:
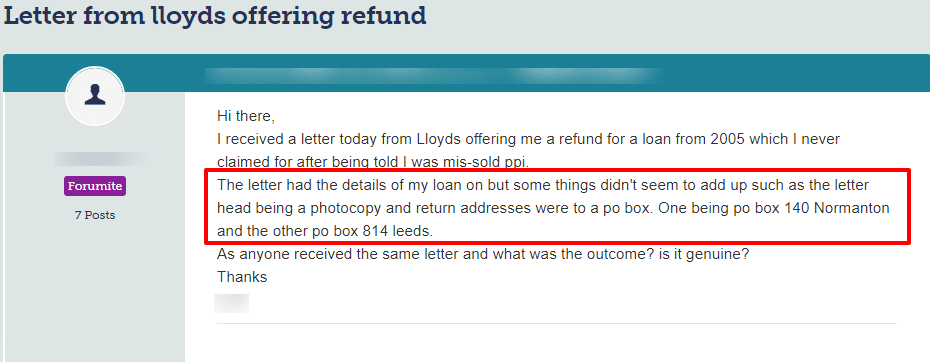
Source: Moneysavingexpert
How should you respond to these letters?
First, open the letter with the PO Box 140 Normanton WF6 1YA return address and discover what it’s about. Then deal with the situation by contacting the sender.
If the letter is addressed to someone else, tell the sender the “person does not live at this address”. Just cross out the name on the envelope and write ‘not known at this address’ across the envelope and pop it back in a post box. The sender should update their records once they receive the letter.
You don’t have any obligation to tell the sender anything else if they ask you to!
That said, reach out to the sender if the letter is addressed to you. Get in touch with the sender and deal with the problem head-on. Ask the sender to ‘prove’ the debt is yours!
Don’t admit, sign or pay anything to the sender until they prove you owe the money!
Understand your debt options
Thrifty Family can introduce you to The Debt Advice Service for free debt advice. Thrifty Family does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
Thrifty Family does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. Thrifty Family is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Do you owe money on a debt?
As mentioned, ask the sender to prove the debt is yours by sending a ‘prove the debt’ letter to them. Whether the letter is from the lender or a debt collection agency, dealing with the situation early makes for a better outcome.
Don’t just take their word for it! Whether it’s the original lender or a debt collector, they must provide hard proof you owe the money.
In short, they must send you an authenticated copy of the agreement/contract you signed.
What happens if the sender can’t prove the debt is yours?
You shouldn’t have to fork out any money to the sender if they can’t provide you with proof the debt is yours. Moreover, the sender should stop contacting and if they don’t, it could be seen as harassment which is against the law!
Is the debt statute-barred?
Debt collection agencies often buy older debts and then try to collect on them. Write back to the sender telling them the debt is statute-barred if it’s at least six years old because it falls under the Limitation Act.
The sender should stop contacting you although they may still ask you to pay which you can refuse to do. Plus, courts won’t hear cases about statute-barred debts so you won’t get a CCJ!
However, although the debt is unenforceable, it still exists. In short, the debt would still remain on your credit history.
Also, there are criteria attached to whether a debt is statute-barred or not which I’ve listed here:
- First, you mustn’t have paid anything to pay off the debt in the last six year
- Second, the creditor hasn’t got a CCJ against you over the debt during that period
- Third, you never admitted owing the money or contacted the creditor in the last six years
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
Thrifty Family introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.
Natasha
Very helpful and informative thank you
Thrifty Family does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. Thrifty Family is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What happens when the debt is proven?
You should try to negotiate a fair, and affordable repayment plan with the creditor if they prove the debt is yours.
If needed, contact one of the debt charities for advice before you do anything else. Their advice could be invaluable when you’re dealing with debt issues and finding it hard to get back on track.
Debt collection agencies and creditors must allow you the time to assess your situation. It means you have the time to sort out the best options to resolve the problem.
Should you ignore letters from PO Box 140 Normanton?
No. Even though you may not recognise the return address or think it’s junk mail, don’t bin the letter. Instead, check out who sent it by opening the letter. Maybe it contains important banking information that needs your attention.
Ignoring a letter about an unpaid debt doesn’t mean the problem goes away. In fact, the problem just gets harder to resolve! Moreover, you’d just keep receiving these letters until you deal with the situation.